Private Equity Firms Charlotte NC: Top Firms in 2026
Key Facts
- Charlotte hosts approximately 22 private equity firms, more than any other North Carolina city. The broader state has roughly 41 PE, growth equity, and mezzanine firms.
- Top Charlotte PE firms collectively manage over $30 billion in assets under management, with Ridgemont Equity Partners alone managing $11 billion.
- Four Charlotte firms raised a combined $7.3 billion in 2025: Ridgemont ($3.975B), Pamlico ($1.75B), Falfurrias ($1.35B), and Plexus ($345M equity fund).
- Ridgemont's Fund V closed at a North Carolina-record $3.975 billion in September 2025, drawing capital from Asia, the Middle East, Western Europe, and Australia.
- Charlotte's PE ecosystem traces its origins to Bank of America and First Union/Wachovia, whose PE investment units were spun off after the 2007-09 financial crisis.
- Dominant investment strategies are middle-market and lower middle-market buyout, with healthcare services, business services, and industrials drawing the most capital.
- Global PE fund closings tracked toward a 20% year-over-year decline in 2025; Charlotte firms recorded their strongest fundraising year in the city's PE history.
Charlotte's Private Equity Market: An Overview
Charlotte's PE market traces its roots to two banking institutions. NationsBank, the Bank of America predecessor, launched a PE unit in 1993 that invested over $3 billion across approximately 140 companies over 15 years. Federal banking reforms following the 2007-09 financial crisis restricted bank capital deployment in PE funds, prompting BofA's CEO Brian Moynihan to wind down the operation.
The existing investment team spun out as Ridgemont Equity Partners in 2010. First Union's PE unit, founded in 1988 and renamed Wachovia Capital Partners after the 2001 bank merger, was managing $2 billion before Wells Fargo acquired Wachovia. Its partners formed Pamlico Capital in 2009, and former BofA CEO Hugh McColl Jr. and CFO Marc Oken launched Falfurrias Capital Partners in 2006.
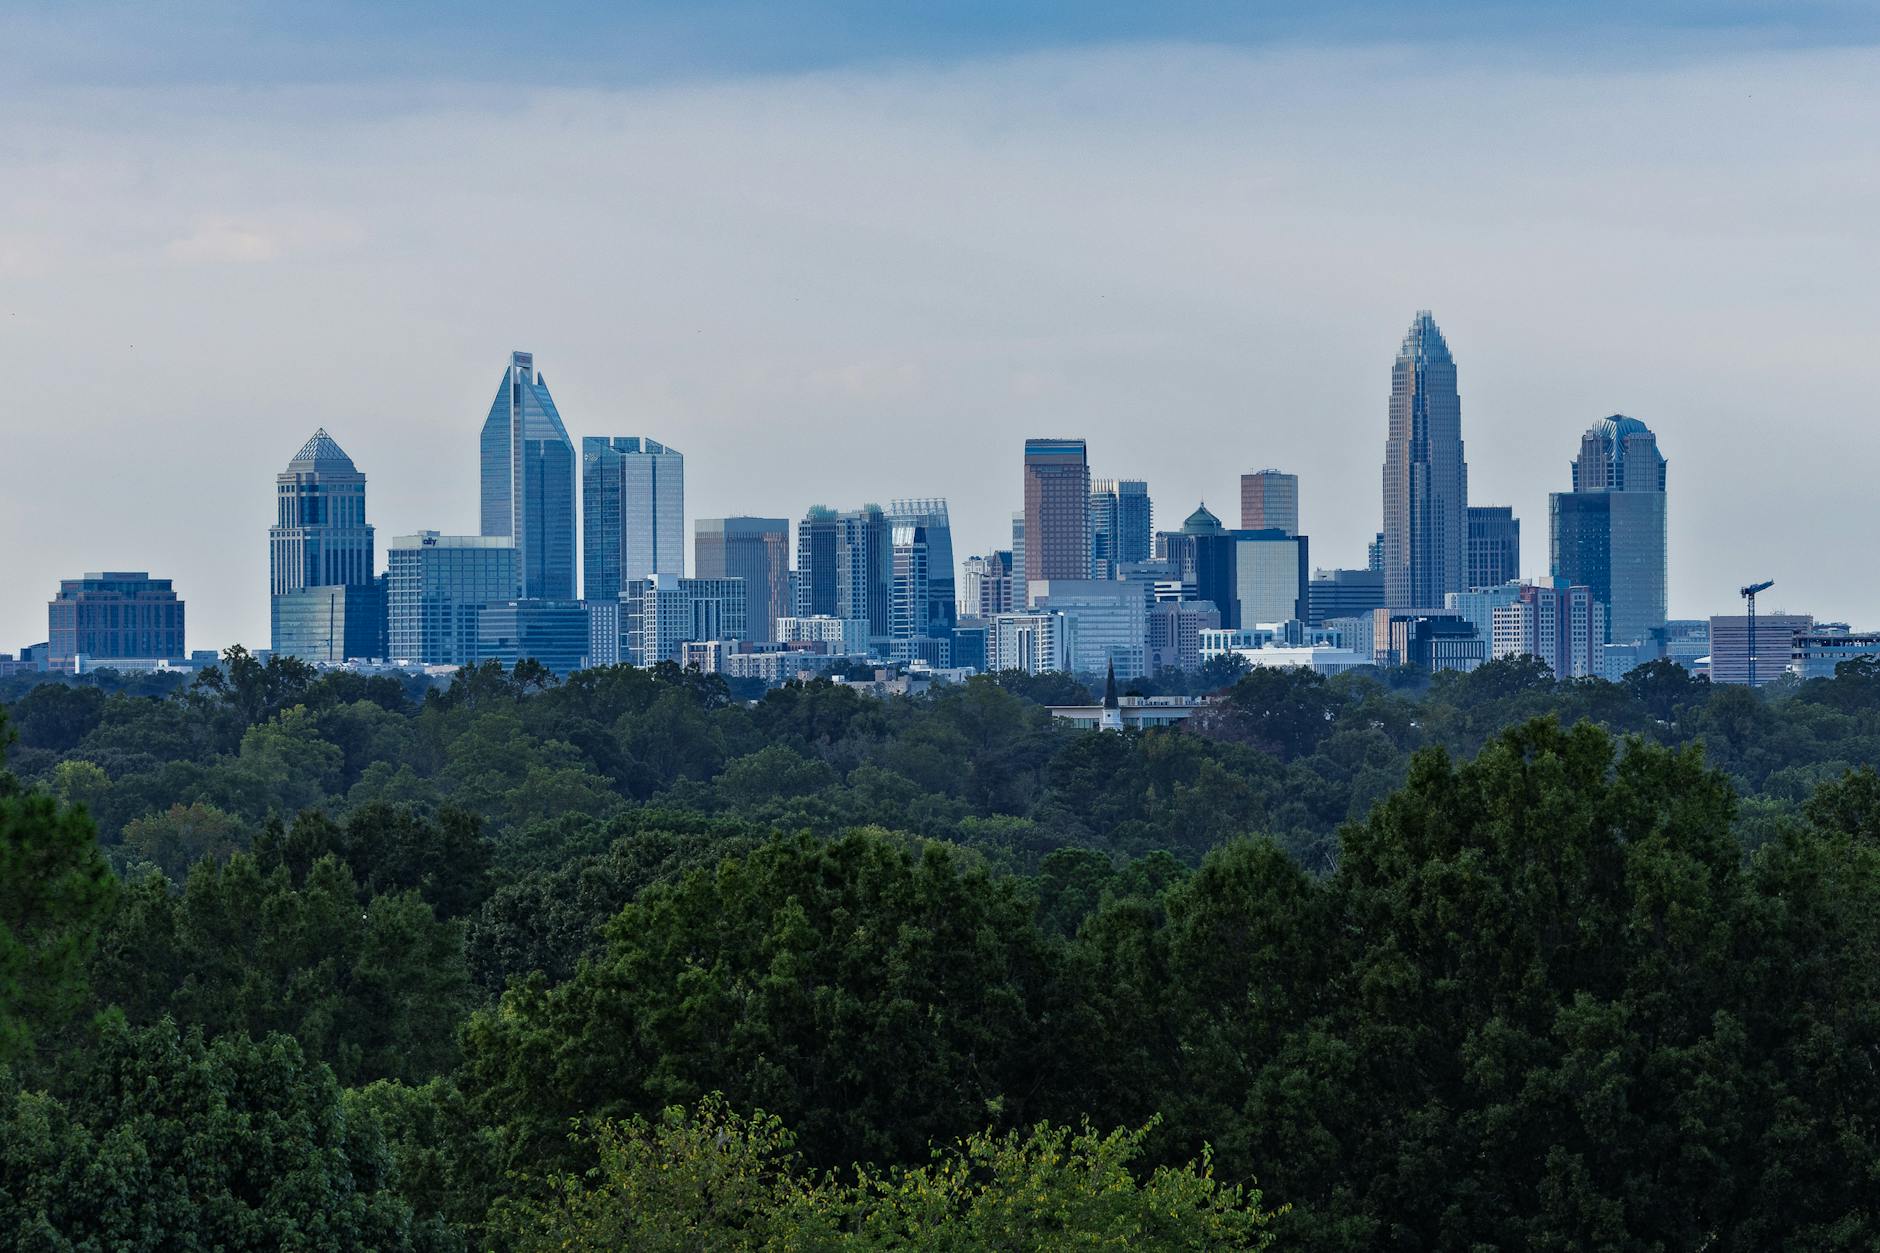
Today approximately 22 PE funds are headquartered in Charlotte, spanning middle-market buyout, lower middle-market growth equity, mezzanine financing, real estate private equity, and vertical SaaS. The top four managers by assets under management account for roughly $22 billion combined. Few U.S. cities outside New York matched Charlotte's 2025 fundraising pace.
The remaining North Carolina PE market includes 19 firms across Raleigh (seven firms, with notable life sciences presence), Durham, Greensboro, and Wilmington. Charlotte investors predominantly target Southeastern U.S. companies, where population growth and business-friendly regulation support consistent deal flow.
Healthcare services consolidation, commercial building services roll-ups, and founder-succession transactions define the dominant investment themes. International LP capital is expanding: Ridgemont's Fund V drew investors from Asia, the Middle East, Western Europe, and Australia alongside its core base of U.S. insurance companies, endowments, and pension funds.
Charlotte Private Equity Firms: Comparison
The city's active PE funds span multiple strategies and market tiers. The table below covers the primary firms, organized by assets under management where data is available.
| Firm | AUM | Strategy | Sector Strength | Best Known For | HQ |
|---|---|---|---|---|---|
| Ridgemont Equity Partners | $11B | Mid-market buyout / growth equity | Business services, industrials, healthcare | Buy-and-build platforms | Charlotte, NC |
| Asana Partners | ~$7B | Real estate PE | Retail / mixed-use urban properties | Urban neighborhood repositioning | Charlotte, NC |
| Pamlico Capital | $3.4B | Growth equity / buyout | Healthcare, technology, business services | Dual growth-and-buyout strategy | Charlotte, NC |
| NovaQuest Capital Mgmt | ~$2.5B | Life sciences PE / product finance | Life sciences, biopharma, veterinary | Biopharma product finance | Raleigh, NC |
| Capitala Group | $2.2B invested | Flexible capital (equity + sub debt) | Diversified lower middle market | Structured capital solutions | Charlotte, NC |
| Falfurrias Capital Partners | ~$1.9B | Mid-market buyout | Consumer products, financial services, tech | Theme-based buyouts, landmark exits | Charlotte, NC |
| Frontier Growth | ~$1.8B | Growth equity | Vertical SaaS, tech-enabled services | Niche software investing | Charlotte, NC |
| Plexus Capital | ~$1.7B equity | Mezzanine / structured capital / PE | Diversified lower middle market | Flexible debt-and-equity capital | Charlotte/Raleigh, NC |
| Carousel Capital | $1.5B+ | Lower mid-market buyout | Healthcare, business services, consumer | Zero forced CEO changes since 2006 | Charlotte, NC |
| Kian Capital Partners | $400M | Lower mid-market buyout / growth | Diversified, first-time PE | Inaugural PE funding specialist | Charlotte, NC |
| Summit Park | N/A | Lower mid-market buyout / growth | Services, consumer, industrial | 50-plus investments, founder-friendly | Charlotte, NC |
| Broadtree Partners | N/A | Lower mid-market buyout | Industrial and service businesses | Operator-centric model | Charlotte, NC |
The market divides into three tiers. Ridgemont, Pamlico, and Falfurrias target enterprises valued at $100 million to $1 billion. Carousel, Plexus, Summit Park, Capitala, and Broadtree serve the lower middle market, with revenue criteria ranging from $10 million to $150 million. Asana Partners and Frontier Growth operate in distinct asset classes that require separate evaluation frameworks from traditional buyout analysis.
Top Picks by Investment Strategy
Largest AUM: Ridgemont Equity Partners manages $11 billion in total assets. Fund V closed at a North Carolina-record $3.975 billion, drawing 100 LP groups including significant international capital.
Real Estate Leader: Asana Partners holds approximately $7 billion in assets, focused exclusively on mixed-use and retail urban properties. Projects include the Midtown development on King Street in Charleston, South Carolina.
Growth Equity Leader: Pamlico Capital manages $3.4 billion and closed its $1.75 billion Fund VI in March 2025, backed by AlpInvest, HarbourVest, and Lexington Partners.
Top Software Investor: Frontier Growth deploys $5 to $30 million initial checks into vertical SaaS platforms, with approximately $1.8 billion in capital managed and portfolio companies spanning talent solutions, sports management, and podcast technology.
Most Active in Life Sciences: NovaQuest Capital Management combines biopharma product finance and private equity across approximately $2.5 billion in assets. Portfolio investments include Covenant Animal Health Partners and Arvelle Therapeutics.
Strongest Exit Track Record: Falfurrias Capital Partners delivered landmark exits including Bojangles (2011) and Sauer Brands/Duke's Mayo (2025). A $1.35 billion fund closed in March 2025 confirms continued LP confidence.
Southeast Consolidator: Carousel Capital has deployed over $2 billion in PE commitments across six funds since 2006. Portfolio companies have achieved 200% average EBITDA growth, and the firm has not made a forced CEO change in that period.
First-Time PE Specialist: Kian Capital Partners targets companies with $10 million to $150 million in revenue that have never received institutional equity capital, deploying a $400 million fund.
Top Charlotte PE Firms in Detail
Ridgemont Equity Partners
The largest general partner in North Carolina's PE market by total assets, Ridgemont manages $11 billion and closed its fifth fund at a state-record $3.975 billion in September 2025. Its investment thesis centers on middle-market companies in business and tech-enabled services, industrials, and healthcare. Individual investments reach up to $500 million in companies valued between $100 million and $1 billion.
The firm's 70-person team is roughly four times larger than at its 2010 BofA spin-off. Operational resources include recruiting support, technology rollouts, and strategic acquisition planning. The buy-and-build model is visible across the portfolio: Crete United has completed 40-plus acquisitions in commercial HVAC and building automation.
eShipping acquired IL2000 in January 2025 to expand its logistics platform. Strata Information Group added BHA Technologies the same month, deepening its IT services footprint in higher education. Alignment stands out: approximately 40 Ridgemont employees contributed a combined $250 million to Fund V, four to five times the industry average on a relative basis.
Pamlico Capital
Pamlico's defining edge is its dual-strategy structure, running growth equity and buyout investments simultaneously. That flexibility lets the firm serve founders who want minority growth capital and those who prefer a full buyout, a range most single-strategy funds cannot match. The $3.4 billion manager targets middle-market companies in healthcare, technology, and business services.
Co-founders Scott Perper, Watts Hamrick, and Eric Eubank II have led Pamlico since its 2009 formation following the Wells Fargo acquisition of Wachovia. The $1.75 billion Fund VI closed in March 2025. Portfolio companies include Service Express (data center maintenance), HelioCampus (analytics technology), Becker's Healthcare (B2B media), and Veson Nautical (maritime software).
Veson Nautical's CEO described Pamlico's approach as collaborative rather than directive. That distinction resonates with founders accustomed to operating autonomously.
Falfurrias Capital Partners
Falfurrias built its reputation on theme-based investing, concentrating capital in industry dynamics its partners understand deeply rather than spreading across broad sector categories. The $1.9 billion firm focuses on middle-market consumer products, financial services, and technology.
The BofA executive lineage runs deep. Co-founder Hugh McColl Jr. was BofA's CEO, co-founder Marc Oken was its CFO, and investment committee chair Chet Walker led the original NationsBank PE operation in 1993. That institutional network generates proprietary deal flow unavailable to newer platforms.
Exit quality validates the strategy. The Bojangles sale in 2011 was the firm's first landmark transaction; the 2025 sale of Sauer Brands (owner of Duke's Mayo) added a second high-profile exit. The $1.35 billion fund close in March 2025 reflects LP confidence across multiple economic cycles.
Carousel Capital
The strongest founder-friendly credential in Charlotte's lower middle market belongs to Carousel. Since 2006, the firm has managed over $2 billion across six funds without a single forced CEO change at any platform investment. That record signals genuine partnership rather than financial sponsor control.
Carousel also reports that 83% of its investments since 2006 went to first-time institutional equity recipients. Average EBITDA growth at portfolio companies reached 200%, and average revenue growth reached 167% during Carousel's hold periods. Recent activity includes the CraneWorks recapitalization (industrial equipment, August 2025) and a merger of covR with United Roofing in a roofing services consolidation.
Inc. named Carousel to its Founder-Friendly Investors list for the fifth consecutive year in 2025.
Frontier Growth
Vertical SaaS is a niche that generalist buyout players routinely undervalue, and Frontier Growth has built an approximately $1.8 billion platform around that specialization. The Charlotte fund deploys initial growth equity checks of $5 to $30 million into software companies serving specific industry verticals. Portfolio investments include Wilson Human Capital Group (talent solutions), Sprocket Sports (sports management software), and PodPlay (podcast monetization technology).
The investment thesis rests on a well-documented pattern: vertical software achieves higher customer retention than horizontal platforms because it embeds deeply into industry-specific workflows. Charlotte's position in the Southeast's expanding technology sector provides a recruiting advantage. Competition from coastal mega-funds is less intense here than in San Francisco or Boston, letting Frontier source deals before they enter formal auction processes.
Plexus Capital
Plexus has raised approximately $3.5 billion in total capital across its fund history. Most of this was structured as subordinated debt instruments for lower middle-market growth and succession transactions. The October 2025 close of a $345 million second private equity fund extends the firm's toolkit, enabling equity deployment alongside mezzanine financing in the same deal.
The Charlotte and Raleigh-based firm was co-founded in 2005 by former Centura Bank executives including Bob Anders and Michael Painter. Portfolio companies include ChemReady (water treatment solutions) and ArmorWorks (defense and security products). Partner Alex Bean describes the equity fund as a natural complement to the firm's larger debt-oriented vehicles, serving businesses that need flexible structured capital rather than a single instrument.
Summit Park
Summit Park has completed 50-plus investments representing over $2.1 billion in combined enterprise value since co-founders Bob Calton and Jim Johnson launched the firm in 2006. The Charlotte fund targets businesses with revenue between $20 million and $150 million and EBITDA of $4 million to $15 million across services, consumer, and industrial growth. Its $245 million 2018 fund reflects intentional size discipline: staying smaller than peer funds keeps Summit Park competitive for transactions that mid-market managers bypass.
Portfolio holding Artifact Uprising (premium photo gifts) was featured on the Today Show, and Michelli completed an add-on acquisition of American Scale to deepen its instrumentation platform. Inc. named Summit Park to its 2024 Founder-Friendly Investors list, and the firm holds Top 50 PE Firm recognition in the middle market for four consecutive years.
Kian Capital Partners
Kian Capital fills a specific market gap: profitable founder-led businesses with $10 million to $150 million in revenue that have never received institutional equity capital. Co-founder Kevin McCarthy identified this opportunity while heading Wachovia Securities' Middle-Market Capital Group, where he observed how many qualified companies fell below larger funds' minimum check sizes. The Charlotte firm raised $400 million approximately two years ago, a fund size calibrated to its deal criteria rather than LP appetite.
McCarthy estimates that tens of thousands of U.S. businesses meet Kian's criteria. The firm's approach is relationship-driven and patient, consistent with Charlotte's broader PE culture of building owner relationships over years before structuring a transaction.
Broadtree Partners
Broadtree's strategy centers on what the firm calls an operator-centric model, deploying managing partners with direct industry operating experience as the primary value-add rather than financial engineering expertise. Managing partners David Slenzak, Johannes Zwick, and Brad Batten lead the partnership, and the firm has completed 25-plus acquisitions to date. Investment criteria require majority stakes in privately held U.S. businesses with EBITDA margins above 10% and a history of profitability.
Broadtree's self-description as "founder-favorable" rather than merely founder-friendly makes a specific claim: preserving a company's core values and management culture is a precondition for sustainable value creation, not a marketing feature.
Investment Trends Shaping Charlotte Private Equity
Healthcare Services Consolidation
Healthcare services is the highest-conviction sector across Charlotte's buyout ecosystem. Ridgemont's Crete United has executed 40-plus acquisitions in commercial HVAC and building automation, while Agape Care Group (Ridgemont portfolio) operates hospice services across the Southeast and earned USA Today Top Workplace recognition for two consecutive years. Carousel Capital holds healthcare as a core vertical, and Pamlico has deployed capital into Becker's Healthcare media.
Specialty veterinary health, home health services, and hospice care represent the most active subsectors for platform investment and add-on acquisition activity.
Tech-Enabled Business Services and Vertical SaaS
Software layered onto traditional service delivery has attracted disproportionate capital from Charlotte fund managers. Ridgemont holds eShipping (logistics, acquired IL2000 in January 2025) and Strata Information Group (higher education IT, added BHA Technologies in January 2025). Frontier Growth concentrates exclusively on vertical SaaS platforms.
The shared investment thesis: software-enhanced service businesses carry recurring revenue dynamics alongside the customer relationship advantages of entrenched professional services firms.
Industrial Roll-Ups Driven by Southeast Growth
Industrial services consolidation has accelerated as Southeastern commercial construction and manufacturing activity expands. Ridgemont's Crete United and Carousel's CraneWorks recapitalization (August 2025) represent active buy-and-build programs in building services and industrial equipment. Charlotte's position at the heart of the Southeast growth corridor provides deal flow access that New York-headquartered platforms must travel to replicate.
Founder Succession as the Primary Deal Source
Founder succession is the dominant deal source for Charlotte's lower middle-market funds. An estimated 50,000 U.S. companies carry revenue between $50 million and $1 billion, and Charlotte managers have built investment strategies around the succession wave as founder-led businesses of the 1990s and 2000s approach ownership transitions.
Kian Capital focuses exclusively on companies new to institutional equity. Carousel reports that 83% of its investments since 2006 were first-time institutional equity recipients. Broadtree's model specifically targets succession situations where the founder wants an operationally engaged successor, not a passive financial sponsor.
International LP Capital Expanding the Investor Base
Ridgemont's Fund V marked a structural shift in Charlotte's LP base. The firm deliberately expanded beyond its core of U.S. insurance companies, endowments, and pension funds to include investors from Asia, the Middle East, Western Europe, and Australia. International LPs represent faster-growing capital pools than domestic institutions.
The State of Wisconsin Investment Board anchored Ridgemont's first independent fund in 2013; today the LP base spans approximately 100 investor groups. That expansion reflects growing global recognition of Charlotte fund managers as a distinct investment category.
How to Evaluate Charlotte PE Firms
Sector expertise is the most important initial filter. Ridgemont's head of investor relations has stated publicly that "the notion of being a generalist is just a no go anymore." Verify that a prospective firm holds multiple active portfolio companies in your industry; a single historical investment does not constitute sector depth.
Fund size must align with deal targets. Ridgemont invests in companies valued at $100 million to $1 billion. Summit Park targets EBITDA of $4 million to $15 million. Approaching a fund whose check size is misaligned wastes time for both parties.
Track record across economic cycles matters more than recent vintage performance alone. Review a firm's portfolio through the 2020 COVID disruption and the 2022-23 interest rate cycle to assess how it managed stressed positions. Ridgemont builds relationships with target companies for three-plus years before closing transactions, a discipline that filters out opportunistic deal-making.
For founders, CEO continuity at portfolio companies is a reliable signal. Carousel has not made a forced CEO change since 2006, and recognition on annual founder-friendly investor lists provides independent external validation.
Employee co-investment rates and LP renewal rates reveal alignment. Approximately 40 Ridgemont employees invested $250 million in Fund V, roughly four to five times the industry norm on a relative basis. All prior Ridgemont investors reinvested in Fund V, a unanimous renewal rate that LP due diligence teams treat as a performance proxy. For limited partners, GP co-investment rates and LP re-up rates across vintages are more informative than a single fund's internal rate of return (IRR).
Which Firm Fits Your Needs?
Founders with $10 million to $150 million in revenue seeking a first institutional partner should start with Kian Capital or Broadtree Partners. Both are explicitly structured for inaugural PE transactions. Broadtree's operator-centric model means its managing partners bring direct operating experience in the industries they back, not just financial engineering expertise.
Businesses in that revenue range with healthcare, business services, or industrial exposure should also consider Carousel Capital. Its 25-year Southeast track record and zero forced CEO changes offer a credible alternative to larger groups that might treat them as secondary platform acquisitions.
Businesses with EBITDA above $30 million and enterprise values above $100 million enter Ridgemont and Pamlico territory. Ridgemont suits industrials, healthcare, and tech-enabled services businesses seeking a patient general partner with a 70-person operating team. Pamlico is the stronger choice for technology and business services companies where a growth equity structure is preferred over a full control buyout.
Falfurrias adds thematic conviction and consumer-sector expertise. Its BofA-heritage executive network generates proprietary deal context that generalist funds typically cannot replicate.
Limited partners allocating to the Southeast middle market have clear entry points by strategy. Ridgemont's $3.975 billion Fund V is the primary benchmark for core middle-market buyout exposure, with its 100-LP investor base and unanimous LP reinvestment rate signaling institutional validation. LPs seeking lower middle-market vintage diversification can access Carousel, Summit Park, or Plexus Capital through their next fund cycles.
Life sciences-focused institutions should evaluate NovaQuest Capital Management separately. Its Raleigh-based biopharma product finance strategy has no direct analog among Charlotte-headquartered fund managers.
Methodology
This guide to private equity firms in Charlotte, NC was compiled from firm websites, press releases, publicly disclosed fund close announcements, and verified industry reporting through 2025 and 2026. AUM figures reflect the most recent disclosures available for each firm. Deal and portfolio data are drawn from firm press releases and confirmed news accounts; no figures were estimated or inferred. Inclusion criteria prioritized firms with active investment programs, disclosed AUM or fund close data, and headquarters or primary operations in Charlotte or North Carolina. Raleigh-based NovaQuest Capital Management is included given its $2.5 billion life sciences specialization, which is distinct from any Charlotte-headquartered fund and relevant to evaluating the broader North Carolina PE landscape.
Frequently Asked Questions
Written by
Andre Miller
Business Analyst
Andre Miller is a Business Analyst at ZoomInvestors, covering private equity and venture capital firms across geographies and sectors. His work focuses on deal structures, investor criteria, and the market trends that shape institutional capital flows.
Related Topics
Explore More
Read more articles on our blog