Private Equity Firms Boston: Top Firms in 2026
Key Facts
- Boston hosts 69 or more active private equity and growth equity firms, with some counts exceeding 100 when all strategies are included.
- The seven largest Boston-headquartered fund managers alone control more than $571 billion in combined assets under management, led by Bain Capital at approximately $205 billion.
- Massachusetts has more PE-backed businesses than any state except California; S&P Global data from August 2025 puts 6.11% of the state's private-sector enterprises under PE ownership.
- Buy-and-build is the dominant middle-market strategy: Audax Group has completed 1,400 or more add-on acquisitions across 175-plus platforms since 1999, and Thomas H. Lee Partners has executed 700-plus add-ons representing more than $260 billion in aggregate enterprise value.
- Fund sizes range from $220 million for lower middle-market vehicles to $7 billion for Great Hill Partners' most recent flagship fund.
- Technology, healthcare, business services, and financial technology attract the largest share of Boston PE capital, with buy-and-build consolidation accelerating across all four sectors.
Boston Private Equity: Market Overview
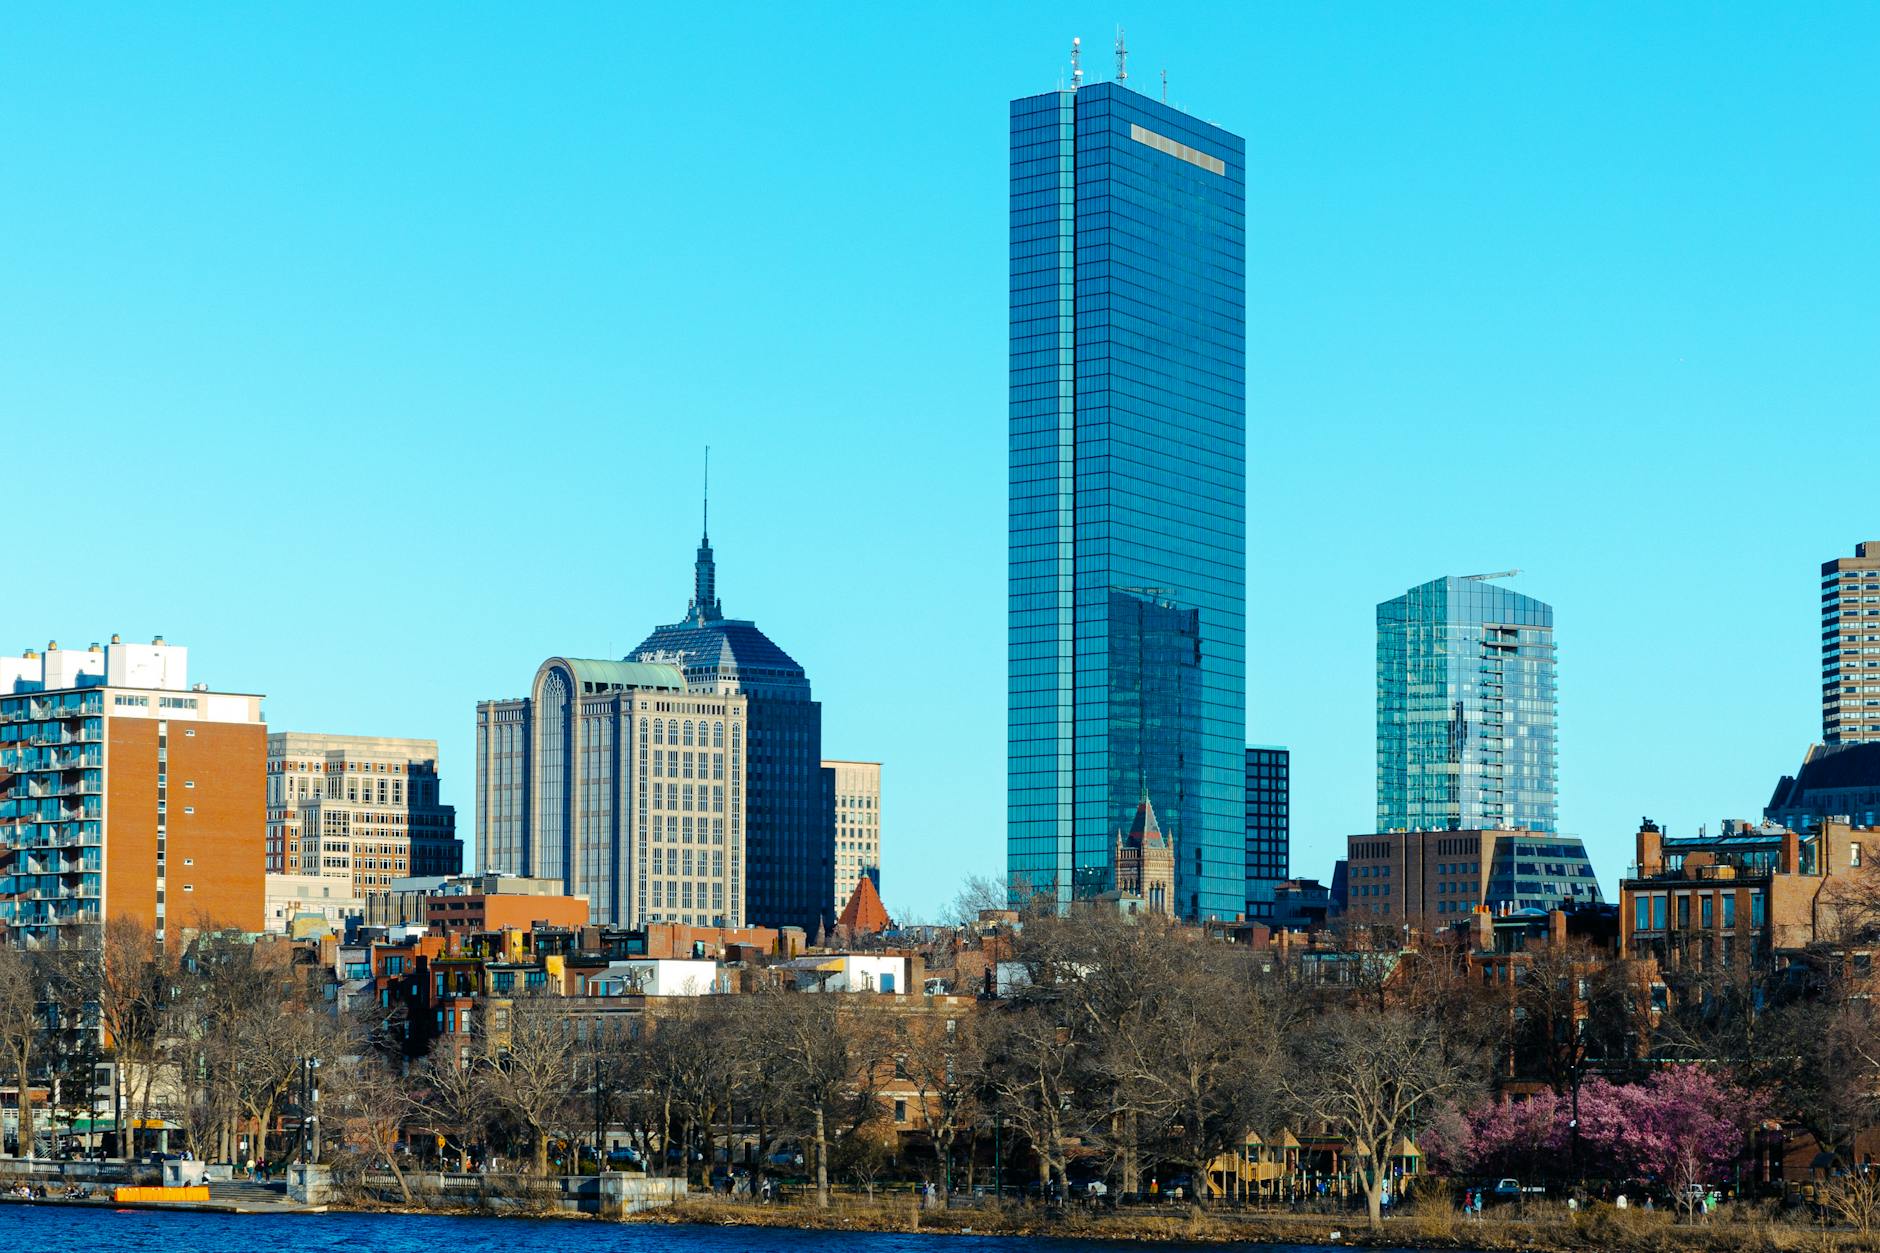
Boston is one of the three largest private equity hubs in the United States, sitting alongside New York and San Francisco in terms of capital concentration and deal activity. Back Bay addresses on Boylston Street and Clarendon Street, and Financial District offices on Arch Street, house some of the most influential fund managers globally. The city's density of institutional capital reflects decades of compounding advantage from Harvard, MIT, and the Route 128 technology corridor, all of which continuously generate deal flow in life sciences, enterprise software, and business services.
Proximity to Kendall Square and the broader Boston biotech corridor gives local PE investors a structural edge in healthcare and life sciences sourcing. Harvard University's endowment management operation spun out Charlesbank Capital Partners in 1998, and the Harvard Business School MBA pipeline feeds senior investment roles across most major Boston firms. This university ecosystem shapes not only the talent supply but also LP relationships with major endowments and foundations.
The market spans every deal size and strategy type. Heritage Holding targets businesses with $1 million to $10 million in earnings before interest, taxes, depreciation, and amortization (EBITDA), while Bain Capital pursues large-cap buyouts and carve-outs globally. Between those poles, a deep tier of middle-market specialists including Audax, Charlesbank, Berkshire Partners, and Thomas H. Lee Partners has built some of the most complete buy-and-build track records in the asset class.
Boston PE Firms: Comparison
The table below covers the largest and most active Boston-headquartered private equity and growth equity fund managers for which verified data is available. Firms are sorted by AUM where data exists.
| Firm | AUM | Strategy | Sector Strength | Best Known For | HQ |
|---|---|---|---|---|---|
| Bain Capital | ~$205B | Buyout, Growth Equity, Credit | Consumer, Healthcare, Technology | Consulting-driven operational model | Boston |
| HarbourVest Partners | $146.7B+ | Fund-of-Funds, Secondaries, Co-Invest | Diversified global PE | 500+ secondary transactions globally | Boston |
| Advent International | ~$94B | Control Buyout | Business Services, Healthcare, Technology | Cross-border buyouts in 42 countries | Boston |
| TA Associates | ~$47.5B | Growth Equity | Technology, Healthcare, Financial Services | 1,667 investments, 459 exits since 1968 | Boston |
| Audax Group | ~$39B | Middle Market Buy-and-Build | Business Services, Healthcare, Software | 1,400+ add-on acquisitions | Boston |
| Charlesbank Capital Partners | ~$23B | Middle Market Buyout, Growth Capital | Business Services, Healthcare, Technology | Harvard endowment spin-out pedigree | Boston |
| Berkshire Partners | $16B+ committed | Middle Market Buyout | Consumer, Business Services, Healthcare | Nine funds, $5.5B Fund IX | Boston |
| Great Hill Partners | — | Buyout, Growth Equity | Software, Fintech, Digital Commerce | $7B Fund IX; first institutional partner model | Boston |
| Thomas H. Lee Partners | — | Middle Market Buyout | Fintech, Healthcare, Automation | $5.6B Fund IX plus $900M Automation Fund | Boston |
| WestView Capital Partners | $2.7B (5 funds) | Growth Equity | IT Services, Healthcare Tech, Software | Minority and majority recapitalizations | Boston |
| Nonantum Capital Partners | — | Lower Middle Market Buyout | Industrial, Business Services, Consumer | Charlesbank spin-out; Inc. Founder-Friendly list | Boston |
| Heritage Holding | $220M committed | Lower Middle Market Buyout | Essential B2B Services | 25 acquisitions since 2016; $1–10M EBITDA focus | Boston |
AUM data is unavailable for Great Hill, THL, WestView, and Nonantum, so the AUM column reflects only confirmed figures. The absence of AUM data for Great Hill and THL does not indicate smaller scale; THL's Fund IX alone closed at $5.6 billion.
Boston's PE landscape is notably more concentrated than most markets. The top five firms by AUM account for the vast majority of local PE assets, yet the middle and lower tiers are equally important for founders and business owners operating at smaller deal sizes.
Top Picks by Investment Strategy
Largest AUM in Boston: Bain Capital (~$205 billion) is the clear leader, operating across private equity, credit, life sciences, and real assets from its 200 Clarendon Street headquarters, with 24 offices across four continents.
Growth Equity Leader: TA Associates has deployed capital in 1,667 companies since 1968 and completed 459 exits, making it the most prolific growth equity investor headquartered in Boston. Investment sizes range from $70 million to $500 million.
Buy-and-Build Specialist: Audax Group has executed more add-on acquisitions than any other Boston PE firm, completing 1,400-plus bolt-ons across 175-plus platform companies in business services, healthcare, industrial technology, and software.
Most Active in Cross-Border Buyouts: Advent International has completed 420-plus transactions in 42 countries, giving it the broadest geographic reach of any Boston-headquartered buyout firm.
Strongest Secondary and Fund-of-Funds Platform: HarbourVest Partners operates across 15 global offices and has completed 500-plus secondary transactions. For limited partners (LPs) seeking diversified private markets exposure, it offers the most complete platform based in Boston.
Top Software and Fintech Investor: Great Hill Partners closed its Fund IX at $7 billion and has backed 301 companies with 114 exits, specializing in software, fintech, digital commerce, and healthcare IT, frequently as the first institutional partner to founder-led teams.
Strongest Automation-Focused Strategy: Thomas H. Lee Partners raised a dedicated $900 million Automation Fund alongside its $5.6 billion Fund IX, the only Boston PE firm with a standalone automation and industrial AI investment vehicle.
Best for Lower Middle Market Founders: Nonantum Capital Partners was named to Inc.'s 2025 Founder-Friendly Investors List for the third consecutive year. A spin-out from Charlesbank, the firm targets family- and founder-owned businesses in industrials, business services, and consumer sectors.
Top Boston Private Equity Firms in Detail
Bain Capital
The largest fund manager headquartered in Boston, Bain Capital manages approximately $205 billion across private equity, growth and venture, credit, real assets, and life sciences. Its defining characteristic is a consulting-derived model: the firm was founded in 1984 by former Bain & Company partners who applied strategic consulting methodology to PE investing. That operating approach persists today in how it partners with management teams on revenue growth, market expansion, and operational improvement. The firm made primary or add-on investments in 940 companies across its history, and 2025 activity included acquiring Service Logic, a commercial HVAC firm, from Leonard Green, and closing a $1.6 billion capital raise for an open-air retail platform with 11North Partners. Founders and management teams seeking a large-cap partner with deep sector resources across healthcare, technology, consumer, and financial services will find few Boston alternatives at this scale.
HarbourVest Partners
HarbourVest is the premier fund-of-funds and secondary market investor based in Boston, managing $146.7 billion or more in assets from 15 offices globally. Its model is fundamentally different from direct buyout firms: rather than acquiring companies, HarbourVest allocates capital across primary PE funds, secondary purchases of existing fund interests, and direct co-investments alongside general partners (GPs). The firm has completed 500-plus secondary transactions globally and logged 130 exits from 269 investments. For institutional LPs seeking diversified private markets exposure without building a direct investment team, HarbourVest offers one of the most complete platforms in the asset class. Its breadth across buyout, venture capital, growth equity, infrastructure, and private credit makes it the natural starting point for endowments and pension funds building private markets allocations.
Advent International
Advent International's defining characteristic is global reach executed from a Boston base. With approximately $94 billion in assets under management, 15 offices in 12 countries, and 420-plus investments completed in 42 countries, Advent operates a scale of cross-border buyout activity that no other Boston-headquartered firm matches. The firm focuses on control buyouts across five sectors: business and financial services, healthcare, industrial, retail and consumer, and technology. Its operationally intensive approach includes dedicated deal teams, a Portfolio Support Group, and a network of more than 100 third-party operating partners. The carve-out and cross-border scale-up playbook is Advent's core competency. Companies with international expansion ambitions or complex carve-out situations are better served here than at firms with a purely domestic focus.
TA Associates
TA Associates has the longest operating history of any major Boston PE firm, having deployed capital since 1968. Its assets under management stand at approximately $47.5 billion. The investment count of 1,667 companies with 459 realized exits gives it a track record depth that few global growth equity firms can match. TA invests as both majority and minority investor across technology, healthcare, financial services, consumer, and business services, with investment sizes typically between $70 million and $500 million. The firm's Strategic Resources Group and Capital Markets Group provide portfolio companies with dedicated functional support beyond capital. TA was named to Inc.'s 2025 Founder-Friendly Investors List, reflecting its reputation for partnership-oriented deal structures. Its five-office global network spanning Boston, Menlo Park, London, Mumbai, and Hong Kong provides portfolio companies with access to international growth markets.
Audax Group
The buy-and-build consolidator of the Boston market, Audax Group manages approximately $39 billion across private equity, private debt, and strategic capital. Its private equity operation has completed 1,400-plus add-on acquisitions across 175-plus platform investments since 1999, a pace of inorganic activity unmatched in the middle market. The Flagship strategy targets control investments in North American middle-market platforms; the Origins strategy extends the same buy-and-build playbook into the lower middle market. Audax Fund VI closed at $3.5 billion in 2018, and the firm's latest fund activity reflects continued appetite for the model in business services, healthcare, industrial technology, software, and consumer. Middle-market business owners entering a sale process where add-on acquisition potential is a key value driver are among the most natural fits for Audax's investment thesis.
Thomas H. Lee Partners
THL's standout characteristic is its parallel track record in both traditional middle-market buyouts and purpose-built automation investing. Fund IX closed at $5.6 billion; the separately managed $900 million Automation Fund makes THL the only major Boston PE firm with a standalone vehicle dedicated to automation and AI-driven industrial transformation. The firm has executed more than 700 add-on acquisitions with aggregate enterprise value exceeding $260 billion across its history. Recent deal activity reinforces its healthcare and technology focus: THL acquired Headlands Research, a multinational clinical trial site network, from KKR in 2025, invested in AMI, the global firmware leader, and backed Bynder, a digital asset management software provider. The combination of flagship buyout scale and a dedicated automation fund makes THL the most relevant Boston partner for companies at the intersection of technology and industrial operations.
Charlesbank Capital Partners
Charlesbank manages approximately $23 billion and occupies a distinctive position in Boston PE: it is the only major middle-market firm with direct lineage from a university endowment. Harvard University's investment management operation spun out the firm in 1998, and Charlesbank has since logged 708 investments and 98 exits across middle-market buyouts, growth capital, and opportunistic credit. Its flagship strategy targets U.S. companies with enterprise values between $200 million and $1.5 billion in business and consumer services, healthcare, industrials, and technology. A separate Technology Opportunities strategy focuses on lower middle-market technology companies with enterprise values between $50 million and $300 million. The credit capability is a meaningful differentiator: Charlesbank can structure deals across the capital structure in ways that pure equity-only firms cannot, which matters in complex recapitalizations and carve-outs where flexible structuring determines deal feasibility.
Great Hill Partners
Great Hill Partners closed its Fund IX at $7 billion, the largest fund closed by a Boston-based specialist buyout firm in recent memory. The firm has backed 301 companies and realized 114 exits in software, fintech, digital commerce, healthcare, and business services. Its positioning as the "first institutional partner" to founder-led, high-growth technology businesses is both a sourcing advantage and a cultural differentiator from larger platform-oriented firms. Great Hill pursues buyout and growth transactions, often taking majority control while preserving management continuity. Software founders who have achieved product-market fit and need operational scale-up capital, a buy-and-build acquisition program, or eventual exit structuring will find Great Hill particularly well-suited to this stage of growth.
Berkshire Partners
Berkshire Partners brings more than four decades of middle-market investing experience to Boston. The firm has raised nine institutional funds with more than $16 billion in committed capital, including Fund IX at $5.5 billion in 2016. It has made more than 130 investments across business services, consumer products, communications and media, healthcare, and industrials, partnering with management teams to accelerate growth organically and through strategic add-ons. Its investment range of $50 million to $500 million in companies with enterprise values between $100 million and $1.5 billion places it firmly in the core middle market. Its longevity and consistent fund-raising pace signal the kind of LP confidence that provides stability through credit cycles.
Nonantum Capital Partners
Nonantum Capital Partners has earned a third consecutive placement on Inc.'s 2025 Founder-Friendly Investors List, a signal that its deal terms and management partnership approach resonate with business owners. A spin-out from Charlesbank Capital Partners established in 2018, the firm targets lower middle-market founder- and family-owned businesses in industrial, business services, and consumer sectors, with Fund II targeting $575 million in commitments. The 2025 acquisition of MSI Express, a co-manufacturing and co-packaging business, demonstrates the firm's appetite for businesses with meaningful operational complexity. Corporate carve-outs and complex family transition situations are also within its mandate.
Heritage Holding
Heritage Holding occupies the smallest-cap institutional segment of Boston PE, targeting essential B2B services businesses with $1 million to $10 million in EBITDA. With $220 million in committed capital and 25 acquisitions since 2016, the firm has built a deliberate lower middle-market franchise in a segment most large-cap Boston firms cannot access efficiently. The 2024 acquisition of Winchester Mechanical and the 2023 acquisition of NCI Datacom demonstrate consistent deal execution in mechanical services and IT infrastructure. For owners of essential services businesses generating $1 million to $10 million in EBITDA who want institutional governance and a buy-and-build growth path without the complexity of a large-cap PE process, Heritage represents the most accessible entry point in the Boston market.
Investment Trends Shaping Boston PE
Buy-and-Build Consolidation at Scale
Platform acquisition followed by systematic add-on acquisitions has become the defining strategy across Boston middle-market PE. Audax alone has executed 1,400-plus bolt-on acquisitions; THL has completed 700-plus add-ons; ABRY Partners has made 1,075 total investments in communications and media. The model works because middle-market sector fragmentation in healthcare services, business process outsourcing, and industrial technology creates predictable arbitrage between acquisition multiples on smaller add-ons and exit multiples on scaled platforms.
AI and Automation Integration Across Portfolio Companies
Every major Boston PE firm now has an explicit AI integration agenda for its portfolio companies. THL made the commitment explicit by closing a dedicated $900 million Automation Fund. Across the broader Boston ecosystem, AI adoption is reshaping everything from clinical trial site operations to enterprise software workflows. Firms that can systematically deploy AI productivity tools across a 20-plus company portfolio are generating EBITDA improvements that pure financial engineering cannot replicate.
Healthcare Services Consolidation
Demographic shifts and payor incentives continue to drive consolidation across healthcare services. THL's acquisition of Headlands Research from KKR, the Hologic deal at approximately $18.3 billion, and consistent activity from specialist firms like Riverside Partners and Boston Millennia Partners reflect the depth of capital targeting clinical services, healthcare IT, and diagnostics. Massachusetts' proximity to major academic medical centers reinforces local deal flow in this sector.
Energy Transition Infrastructure
ArcLight Capital Partners and Denham Capital represent Boston's specialist energy transition investing cohort. Denham focuses on sustainable infrastructure, critical minerals, and private credit across decarbonization platforms; ArcLight has completed 281 investments and 174 exits in power, midstream, and renewables. Ara Partners manages $6.3 billion in assets, with its Fund III at $2.8 billion focused exclusively on industrial decarbonization. The firm requires a minimum check size of $100 million. Capital flows into this subsector are accelerating as regulatory tailwinds and corporate decarbonization commitments create proprietary deal opportunities.
Impact Investing with Competitive Return Expectations
Bain Capital Double Impact Fund has made 58 investments and completed 13 exits in health and wellness, education, workforce, and sustainability, targeting measurable social outcomes alongside market-rate financial returns. This segment has moved well beyond niche status: the Double Impact Fund competes for mid-market deals on the same financial terms as conventional PE vehicles.
How to Evaluate Boston PE Firms
The first screen for any business owner or LP evaluating Boston PE firms is fund size alignment with target deal size. Heritage Holding writes $1 million to $10 million EBITDA checks; TA Associates starts at $70 million per investment. Approaching a firm whose fund is ten times larger than your deal is a poor use of process time.
Track record depth matters more than brand recognition. Examine the internal rate of return (IRR) and multiple on invested capital (MOIC) across full fund cycles, not just the most recent vintage. Firms like TA Associates have 459 realized exits across 57 years; Advent has 581. That exit volume produces statistical confidence in the return profile that a ten-investment track record cannot.
Sector expertise signals value-add credibility. A firm with ten healthcare portfolio companies has a proprietary network of management talent, operating consultants, and commercial introductions that a generalist firm cannot replicate. Ask how many current portfolio companies operate in your sector and what concrete operational resources the firm will deploy.
For founders specifically, the distinction between minority and majority structures is material. TA Associates, Summit Partners, and WestView Capital Partners all offer minority recapitalization options. Most classic buyout firms require majority or full control. Clarifying this upfront prevents wasted process time on both sides.
LPs evaluating Boston fund managers should examine LP composition, co-investment rights, and fee structures alongside performance data. Uncommitted capital available for deployment in the current fund, the pace of capital deployment from recent vintages, and the GP's own capital commitment as a percentage of fund size all provide signals about alignment and deployment discipline.
Which Firm Fits Your Needs?
Founders of technology or healthcare businesses generating $5 million to $50 million in EBITDA have the widest choice in Boston. Great Hill Partners, WestView Capital Partners, Riverside Partners, and Nonantum Capital Partners all target this range, with varied appetite for minority versus majority structures. WestView is particularly well-suited for businesses where the founder wants to retain day-to-day operational control under a minority recapitalization; Great Hill and Nonantum prefer majority ownership alongside an active buy-and-build acquisition program.
LPs building diversified private markets allocations should start with HarbourVest for secondary and fund-of-funds exposure, which provides vintage diversification and access to strategies that are otherwise closed to smaller allocators. Institutional LPs with the scale to participate in direct co-investment programs will find Bain Capital and Advent International the most relevant Boston options at the large-cap end.
Business owners in essential B2B services, light industrial, or consumer sectors with EBITDA below $10 million have fewer institutional options nationally, but Boston is unusually well-served at this end: Heritage Holding, Nonantum Capital Partners, and Artemis Capital Partners all operate purpose-built lower middle-market strategies. The buy-and-build potential in these sectors, combined with Boston firms' operational infrastructure, often justifies a PE process over a strategic sale at these deal sizes.
Methodology
This guide covers private equity and growth equity firms with headquarters or significant offices in Boston, Massachusetts. Firm selection is based on confirmed AUM, fund size, investment activity, and publicly available deal data from industry publications and firm disclosures. AUM figures reflect the most recent confirmed data available, primarily from 2024 and 2025 firm disclosures. Only firms where verifiable data supports their profiles are included; all AUM and deal figures reflect documented sources. Pure venture capital firms and real estate-only managers fall outside this guide's scope. Coverage spans private equity firms in Boston across the full strategy spectrum, from lower middle-market buyouts to global large-cap platforms, to serve founders, LPs, and advisors evaluating the market.
Frequently Asked Questions
Written by
Andre Miller
Business Analyst
Andre Miller is a Business Analyst at ZoomInvestors, covering private equity and venture capital firms across geographies and sectors. His work focuses on deal structures, investor criteria, and the market trends that shape institutional capital flows.
Related Topics
Explore More
Read more articles on our blog